UKG Wallet
UKG, Inc.
- 4.6
- 1.84K Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
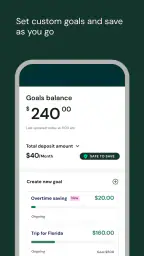
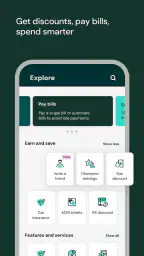
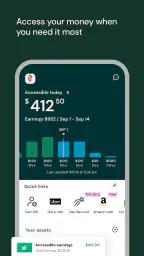
UKG Wallet Pros and Cons
Pros
- Centralizes pay, benefits, and workplace information in one app.
- Useful for checking payroll details while away from a computer.
- Supports access to employer-specific HR services and resources.
- Can reduce paperwork by providing digital employee documents.
- Helpful for employees working across multiple locations or schedules.
Cons
- Most features depend on your employer’s UKG configuration.
- Requires company login details and may need extra verification steps.
- Some functions may be unavailable outside scheduled work periods.
- Payroll and benefits updates can depend on employer processing times.
- The interface and available tools may differ significantly between workplaces.
 Analysis by All-app
Getting access to earned wages can be useful when an unexpected bill arrives before payday, and that is the practical idea behind UKG Wallet. I reviewed it as a business app from UKG, Inc., focusing less on the promise of faster access and more on the questions that matter in real use: what control the employee has, when account details become important, and how carefully the app fits into an existing payroll routine.
The app is free and aimed at everyone from an age-rating perspective, but its usefulness is not the same for every phone owner. It is most relevant to people whose employer supports the service and connects it with their work and pay arrangements. If that connection is not available through your workplace, installing the app alone will not turn it into a general-purpose banking replacement. That distinction is the first thing I would keep in mind before spending time setting it up.
What UKG Wallet is really useful for
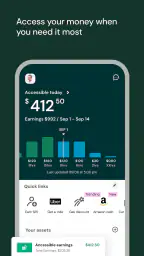
In everyday terms, this is an earned-wage access tool rather than a full personal-finance headquarters. Its central purpose is to give eligible workers access to wages they have already earned, instead of making them wait for the normal payroll date. That can make a meaningful difference for someone handling a small timing problem, such as a utility payment due tomorrow or a necessary purchase between paychecks.
I would not approach it expecting detailed budgeting, investment tracking, bill negotiation, or the broad account ecosystem offered by a traditional bank. Its value is narrower, and that is actually helpful when the need is narrow too. A focused app can be easier to understand than a large financial platform filled with features that have nothing to do with accessing earned pay.
The important word is “eligible.” Wage availability depends on the employer and the payroll setup behind the account, so the app should be viewed as part of a workplace process rather than an independent service that works identically for everyone. Before relying on it for a deadline, I would check the amount shown as available and the timing displayed in the app instead of assuming that every shift or payroll entry appears immediately.
How it fits a normal payday routine
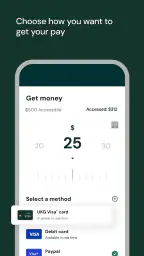
Imagine that I have worked several shifts, but my regular payday is still a few days away. A car repair creates a short-term gap. In that situation, I would open the app, review the amount presented as available, and decide whether taking part of it now is worth reducing what arrives on the regular payday. That last step matters: early access is not extra income. It changes the timing of money I have already earned.
For a careful user, the best workflow is to treat the available balance as a planning signal, not as permission to withdraw everything. I would first identify the exact amount needed, leave a cushion for ordinary expenses, and then review the confirmation screen before approving anything. This habit reduces the chance of turning a small emergency into a larger cash-flow problem later in the pay cycle.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
That makes the app more useful for occasional timing issues than for routine overspending. If I needed early access every pay period just to cover normal expenses, I would take that as a sign to review my budget rather than treating the app as a permanent substitute for sufficient income.
Why the app has attracted attention
The public response is encouraging: UKG Wallet holds a 4.6 average from around 12 thousand ratings, with about 1.8 thousand written reviews. It has also passed 100 thousand installs. Those figures suggest that the idea is reaching a substantial audience, but they do not remove the need to check whether the service matches my employer’s setup or whether the withdrawal terms suit my situation.
The app was released on December 21, 2021, and the current version is 1.0.25. It requires Android 10 or newer, which is worth checking before installation on an older device. I also like seeing the version requirement treated as a practical detail rather than an afterthought: a financial app that cannot be updated on a compatible device is not a good tool for urgent situations.
Because the developer is UKG, Inc., users may recognize the connection with workplace administration and payroll services. That context gives the app a different role from a standalone money app. The experience depends on the relationship between the employee, the employer, and the payroll information being made available, so trust is not only about the interface. It is also about understanding where the displayed wage figure comes from and how it fits into the employer’s process.
Trust, controls, and moments that deserve care
I’d use this section to focus on the checks that make a wage-access decision feel deliberate rather than rushed: confirming the employer connection, reviewing the amount and destination, and considering how an early transfer affects the next payday. A useful extra habit is to decide in advance what kind of shortfall would justify using the app, so a stressful moment does not make the choice for you. That naturally leads to the practical question of how the app fits into everyday use.
What I would verify before relying on it
My first trust check would be whether the account clearly identifies the employer connection and the wage information being used. A user should be able to distinguish earned-pay information from ordinary bank-account balances. If a screen presents an amount available for access, I would read the surrounding explanation rather than treating that number as a guaranteed final paycheck total.
I would also pay attention to confirmation steps. Financial actions deserve a deliberate review of the amount, destination, timing, and any conditions shown before completion. A good personal habit is to pause at the final screen and ask, “Will I still be comfortable with my next regular pay after this?” That question is more useful than simply asking whether the amount is technically available.
Account controls matter just as much as access. I would keep the phone protected with the device’s own lock, avoid approving a transaction while distracted, and sign out or secure the account if another person regularly uses the phone. These are simple measures, but an app connected to wage information should not be treated like a casual shopping application.
I would also keep notifications under review. A notification can be convenient when it tells me that new wage information is available, but financial details appearing on a lock screen may not suit everyone. Checking the phone’s notification settings and choosing what can appear publicly is a small privacy decision that many people overlook.
Data-sensitive moments in daily use
The most sensitive moments are not necessarily the first launch or the logo screen. They are the points where I enter account credentials, view pay-related information, confirm a transfer, or change an account setting. I would slow down at each of those steps and make sure I am using the intended app, the correct employer connection, and a private network when possible.
I would avoid making an urgent wage-access decision on a shared device. Even if the app itself is convenient, a shared phone can expose notifications, saved credentials, or account screens to another person. My preferred approach would be a personal device with a current operating system, a screen lock, and no unnecessary sharing of the session.
Another useful discipline is to review the account after an action rather than assuming everything worked exactly as expected. I would look for a status or confirmation inside the app and keep an eye on the next payroll result. If the displayed amount, timing, or destination does not match what I approved, I would stop making additional requests and contact the appropriate support channel through the workplace or app.
That cautious approach is especially important because early wage access can feel like free flexibility in the moment. The money is earned, but the timing affects the rest of the pay cycle. The app can help with a short gap, yet it cannot remove the underlying obligation to manage rent, food, transport, and recurring bills.
User agency is the deciding factor
I value the app most when it lets me make a small, informed decision instead of pushing me toward a maximum withdrawal. The practical sign of user agency is not simply having access; it is being able to review the amount, understand the consequence, and choose whether to proceed. I would use it selectively, for a defined need, and record the amount in my own budget so the next payday does not come as a surprise.
A useful personal rule is to request only what solves the immediate problem. If a bill is short by a modest amount, there is little reason to take the entire available balance. This is one of the less obvious advantages of a focused earned-wage tool: it can be used as a precise bridge rather than a broad spending account, provided I keep control of the decision.
I would also compare the app’s convenience with the alternatives available to me. A traditional bank account gives a clearer long-term view of deposits, recurring payments, savings, and balances. A budgeting app may be better for understanding spending patterns. An employer’s normal payroll process remains the simplest option when I can wait. UKG Wallet makes more sense when the problem is specifically the gap between work already completed and the scheduled payday.
For someone who dislikes managing several financial tools, that narrow focus may be reassuring. For someone looking for a complete money-management system, it may feel limited. The right choice depends on whether early access to earned wages is the actual need or merely one small part of a larger financial problem.
Where friction can appear
The employer connection is both the app’s strength and its main limitation. Since the service is tied to workplace and payroll arrangements, the experience may not be equally useful after changing jobs, working irregular hours, or dealing with delayed time records. I would not plan an important payment around an amount that has not yet appeared as available in the account.
There is also a mental cost to checking wage availability too often. Seeing an available figure can encourage spending before the normal pay cycle is complete, even when the original intention was only to handle emergencies. I would keep the app in a supporting role and avoid opening it as a substitute for a regular budget review.
People who want extensive transaction categorization, savings goals, credit tools, or a consolidated view of multiple accounts should probably choose a banking or personal-finance app designed for those tasks. UKG Wallet is not the better option simply because it is free. Free access is useful, but the real question is whether its limited purpose matches the situation.
Questions I would answer before installing
Will it work for every employee? I would assume no until my employer confirms that the service is supported for my role and payroll arrangement. The app is built around access to earned wages, so workplace eligibility is more important than the download itself.
Can it replace my bank? In my view, no. I would use it for the specific earned-pay function and continue using my normal bank account for deposits, bills, savings, and broader money management.
Should I use it for regular spending? I would be cautious. Occasional access can help smooth a temporary mismatch between income and a due date, but relying on it repeatedly may hide a budget shortfall and leave less money on the standard payday.
What should I check before confirming an action? I would review the amount, the expected timing, the destination, and the effect on the next paycheck. I would also make sure the account is secure and that no private financial information is visible to people nearby.
Is it suitable for an older phone? The listed minimum is Android 10, so I would check the device operating system before planning around the app. A compatible, updateable phone is especially important when the app is used for account access rather than occasional entertainment.
My cautious verdict
I see UKG Wallet as a practical, narrowly focused business app for employees who have access through their workplace and occasionally need to bring earned wages forward. Its strongest quality is not that it makes money appear; it gives a user another way to manage the timing of money already earned. Used with a specific purpose and a clear plan for the next payday, that can be genuinely helpful.
My recommendation comes with boundaries. I would verify the employer connection, protect the account like any financial service, read each confirmation carefully, and avoid treating the available amount as spare cash. I would choose a regular bank or budgeting tool when I need a complete view of my finances, and I would skip this app if my workplace does not support the underlying service.
For the right employee, the free app is worth considering because it addresses a real cash-flow problem without pretending to be a complete financial life manager. I would recommend it to a friend who needs occasional flexibility and is comfortable making deliberate decisions. I would not recommend using it as a habit that replaces budgeting, saving, or waiting for the normal payroll cycle.
Frequently Asked Questions
What is UKG Wallet and how does it work?
UKG Wallet is a financial wellness feature connected to eligible UKG workplace systems. It may allow employees to view earned wages and, depending on their employer’s setup, access a portion of those wages before the regular payday. After signing in through the supported UKG environment, users can review available balances, transfer options, fees, and transaction history. Features are not identical for every employer or employee.
Who can use UKG Wallet, and is it available through every employer?
UKG Wallet is not automatically available to everyone who downloads the app. Access generally depends on whether your employer has enabled UKG Wallet and whether you meet the employer’s eligibility requirements, such as payroll status, employment type, or account configuration. You may also need valid UKG login credentials and a supported payment method. Contact your employer or payroll department if the service does not appear.
Does UKG Wallet let me receive my salary before payday?
In participating workplaces, UKG Wallet may provide access to wages you have already earned before your scheduled payday. The amount available can change as payroll data is updated, and it may not equal your full expected paycheck. Transfers can also depend on processing times, account verification, employer rules, and the selected delivery method. Review the confirmation screen carefully before requesting a transfer.
Are there fees for using UKG Wallet or transferring money?
Some UKG Wallet services may be free, while certain transfer methods or optional features can involve fees. The exact cost depends on your employer’s program, the destination account, processing speed, and other applicable terms. Before confirming a transaction, check the displayed fee and total amount. Users should also remember that early wage access is not additional income; it is an advance against earned pay.
Is UKG Wallet safe, and what should I do if I have login or payment problems?
UKG Wallet is designed to use account authentication and security controls, but users should still protect their credentials, enable available security options, and avoid signing in through suspicious links. If you experience login issues, missing wages, delayed transfers, or an unrecognized transaction, first check the app status and account details, then contact your employer’s payroll or HR team and UKG support through official channels.